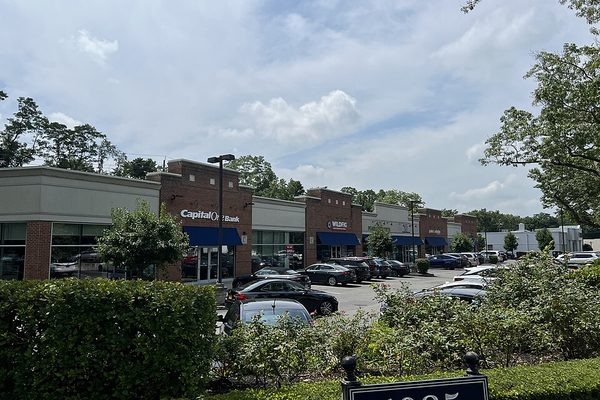
What a retail property program covers
- Commercial property for each building at replacement cost, plus signs and outdoor property such as light poles, where covered.
- Loss of rents for rent lost while the center is repaired after a covered loss.
- General liability for parking lots, sidewalks, walkways and common areas.
- Umbrella / excess liability, especially important for properties with heavy foot traffic.
- Equipment breakdown for rooftop HVAC and electrical systems the owner is responsible for.
Why the parking lot matters
Slip-and-fall and trip claims are a common liability claim for retail properties. Underwriters ask who handles snow and ice removal, how lighting and pavement are maintained, and whether that work is documented. If a contractor handles snow removal, its contract should require its own liability insurance naming you as additional insured.
Tenant mix and leases
Restaurants, gyms, entertainment venues and other high-traffic or cooking tenants are rated differently from offices and soft-goods stores, so underwriters ask for the tenant list. Leases should require tenants to carry general liability naming the landlord as additional insured, and many also require tenants to insure their improvements and contents. Collect certificates every year and keep them on file.
Street-level retail in NYC
In New York City, much retail sits on the ground floor of buildings with apartments or offices above. See mixed-use building insurance and office building insurance.
Shopping centers and retail buildings are quoted by Jacob directly. Send a message or call 646-494-4355. If you also own NYC apartment buildings, the instant estimate gives a quick range for those.
Frequently asked questions
Do you insure shopping centers outside New York?
Yes. We insure shopping centers, strip centers and retail buildings across the United States.
Who is responsible for a fall in the parking lot, me or the tenant?
It depends on the lease and who controls the area. Common areas are usually the landlord's responsibility, which is why landlord general liability and good maintenance records matter. Your attorney should review the lease terms.
Does a vacant storefront affect my insurance?
It can. Insurers want to know about vacancies, and long or large vacancies can trigger restrictions in some property forms. Tell us when occupancy changes. See vacant building insurance.
What do you need to quote a shopping center?
The address, building sizes and construction, year built and updates, the tenant list and rent roll, parking lot details, five years of loss runs and the current premium.